

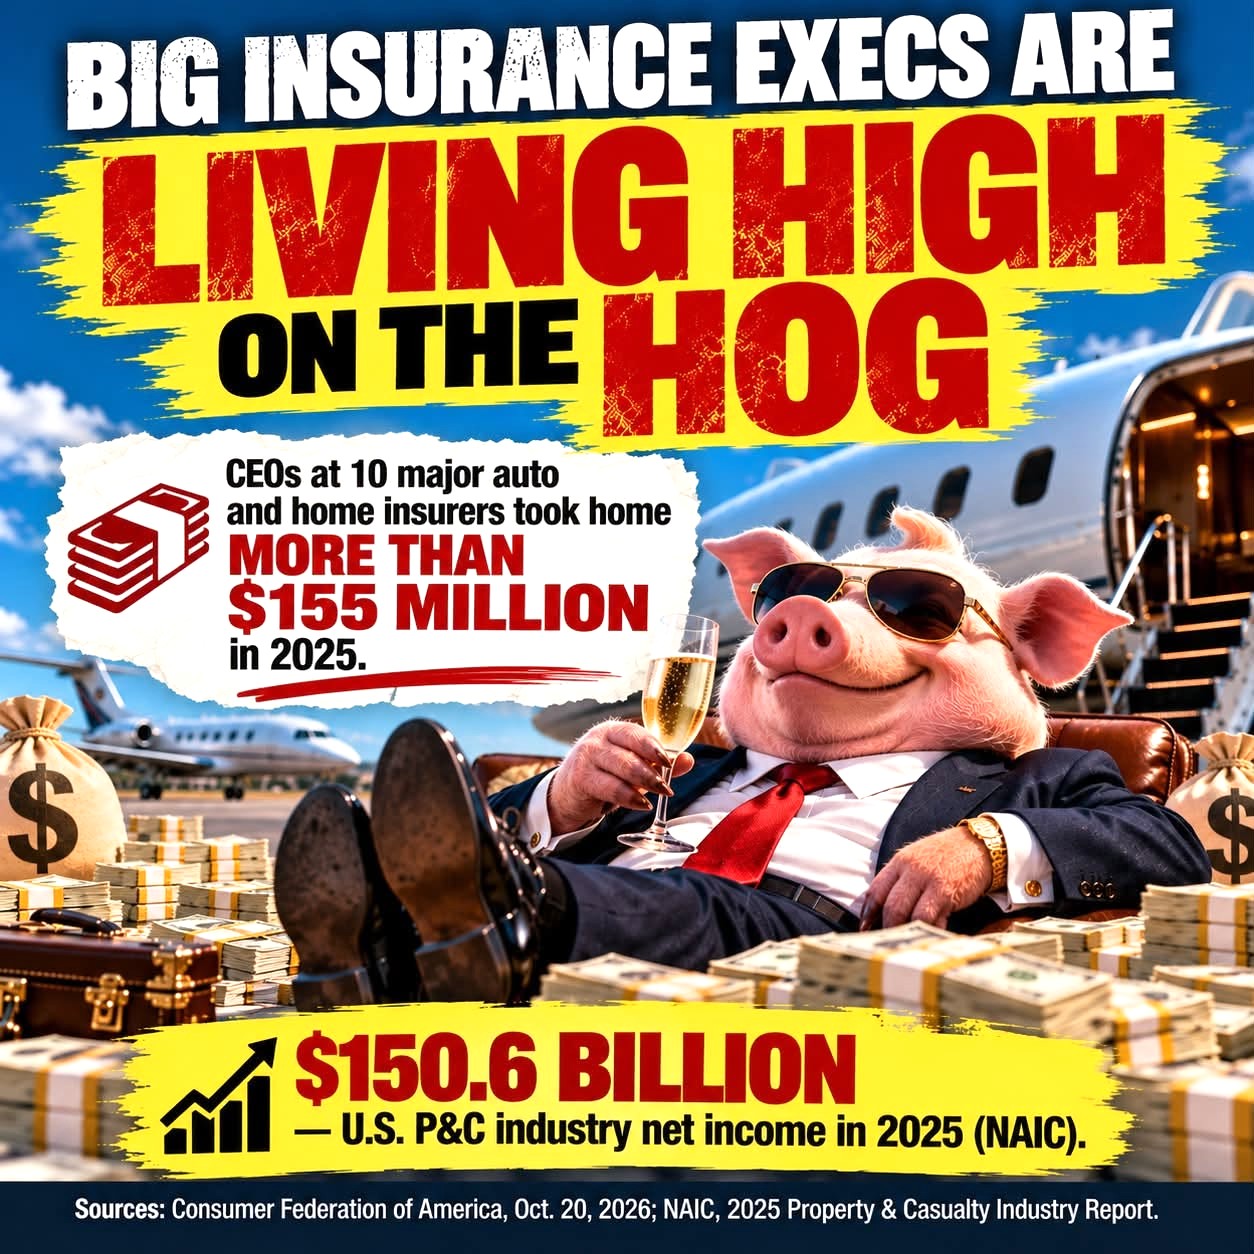
graphic courtesy of Real Reform Louisiana/Facebook
According to the National Association of Insurance Commissioners, the property and casualty insurance industry reported $150 billion in profits in 2025. Real Reform Louisiana Executive Director Ben Riggs says insurance companies make money not only from premiums, but also by investing those dollars, earning underwriting income and delaying claims.
“A recent report indicated that the property and casualty insurance industry, as a whole, makes about $8.8 million a day for a denied claim or delayed claim,” Riggs said.
Riggs says insurance executives are cashing in on these massive bonuses.
“According to the Consumer Federation of America, 10 of the nation’s largest auto and home insurers paid out $155 million to their executives, which was an 18% pay raise over the previous year,” Riggs explained.
Riggs is calling on Louisiana lawmakers to act. He says insurers should not be allowed to pass the cost of executive bonuses, advertising, lobbying and political spending on to policyholders, all while recording record profits. He adds that insurers should have to justify their costs to regulators before rates go up.
“Commissioner Temple and the legislature have made it easier for this to happen. They’ve made it easier for insurance companies to raise their rates without prior approval,” Riggs noted.
A spokesperson for the Louisiana Department of Insurance says relying on national profit data does not reflect the reality of Louisiana’s insurance market. LDI says the cost of insurance is directly related to the losses insurers pay in claims and unfortunately, Louisiana experiences some of the highest losses in the country.
LDI Deputy Commissioner of Public Affairs John Ford issued the following statement:
Relying on national profit data that does not reflect the reality of Louisiana’s insurance market is misleading, and Real Reform should know better. Home and auto insurers have historically had significantly higher losses in Louisiana compared to the national average. Over the most recently reported decade, homeowners insurers had an average annual underwriting loss of -38.9% in Louisiana, which is far worse than the national average of a -0.4% loss.
In that same timeframe, Louisiana auto insurers had average annual losses of -4.1% and -28.2% in the personal and commercial lines, which are two and four times as much as the national averages for those figures (-2% and -7.3%, respectively).
The cost of insurance is directly related to the losses insurers pay in claims, and unfortunately, Louisiana experiences some of the highest losses in the country. Those losses are driven by things we cannot control, like our hurricane exposure, and by things we can control, like resilient construction and abuse of the legal system.
Commissioner Temple has worked closely with the legislature and Governor Landry over the past three years to promote structural resilience and enact insurance and legal reform aimed at reducing those losses. Over the past year, homeowners and auto insurance have started taking more rate decreases, as well as fewer and less costly rate increases, but we have much more work to do to make insurance more available and more affordable in Louisiana.




Comments